
Making Tax Digital · Landlords
Property repairs and capital improvements: deciding how to treat the cost
ONLY£15A MONTHA repair generally restores something, while an improvement can create or enhance an asset.
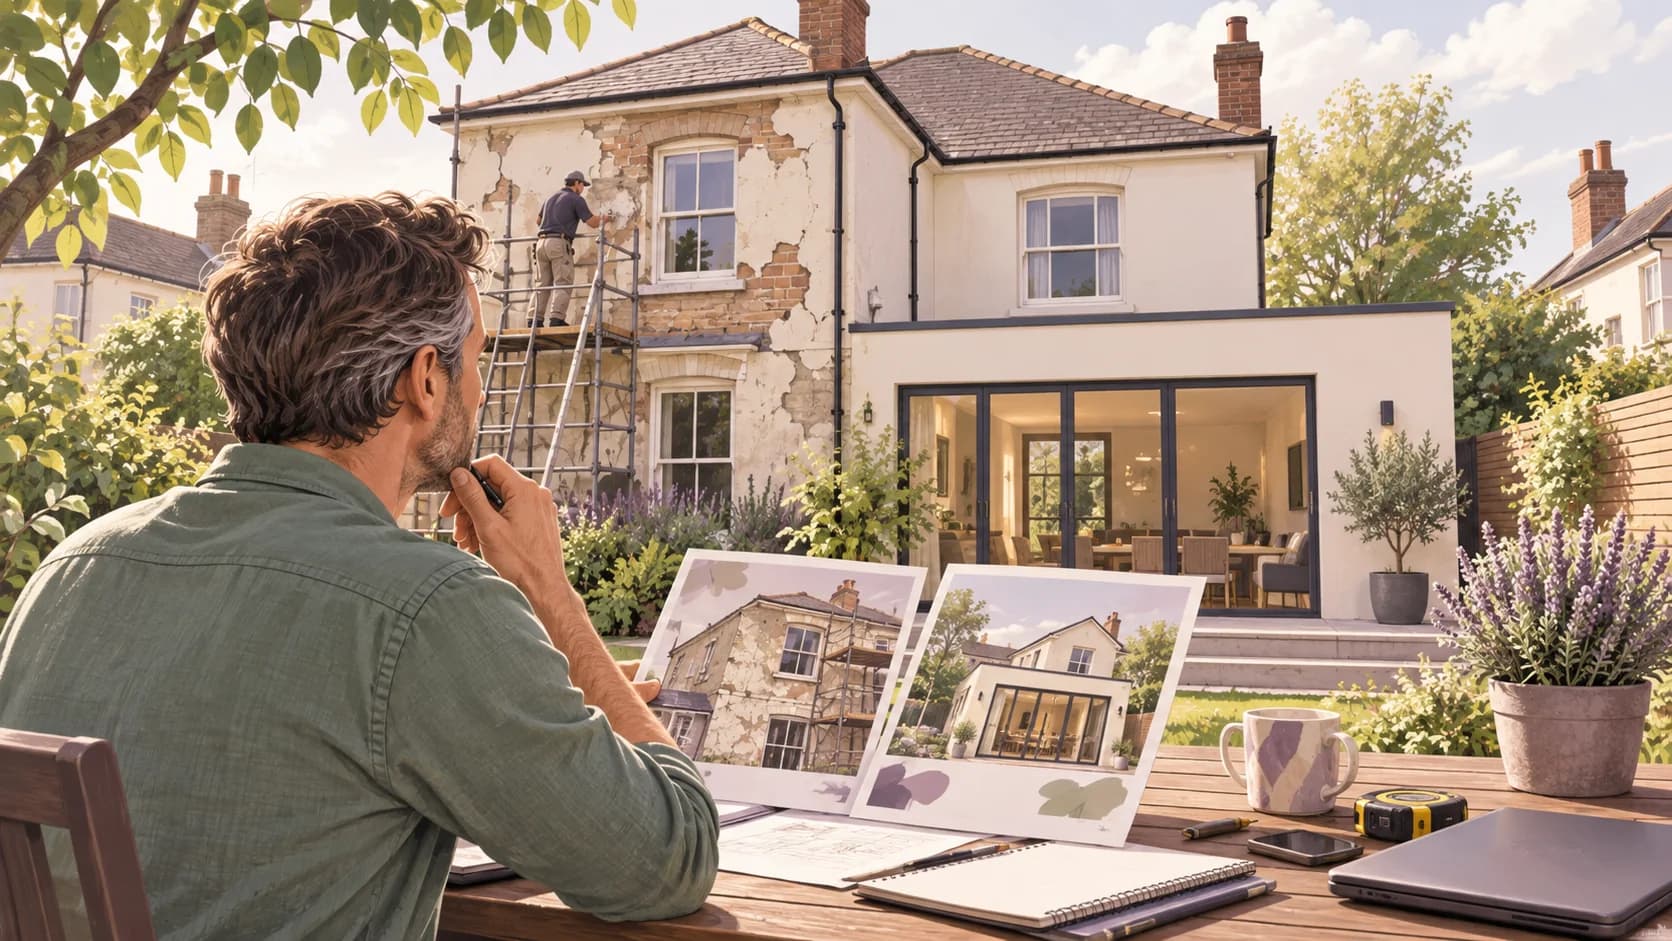
A repair generally restores something, while an improvement can create or enhance an asset. The distinction affects how a landlord's expenditure enters the tax calculation. The invoice heading “maintenance” does not settle the question, and using a modern replacement does not automatically make every job capital.
Look at the work in context
HMRC's rental-income guidance explains repairs and improvements. Replacing a worn component with its modern equivalent can still be a repair. Adding something substantially new or improving the property beyond restoration may be capital.
Consider the whole project and the condition of the property when acquired. Work needed to make a derelict or unusable property fit for letting can require different analysis from routine repairs during an established letting business.
Ask for useful invoice detail
A project may contain distinct repair and improvement elements. Obtain a breakdown based on the actual work and costs, rather than assigning an arbitrary percentage after the event. Retain surveys, specifications and photographs where they explain the change.
Capital expenditure is not necessarily lost for every tax purpose, but future Capital Gains Tax relief depends on its own conditions. Do not promise that every disallowed rental expense will automatically reduce a later gain.
Worked comparison: restoring and extending
A landlord replaces a failed boiler with a suitable modern equivalent serving the existing property. Another project adds a new extension with additional living space. The two jobs need different analysis even if the same contractor performs both.
If one invoice covers both, request a proper breakdown. Treating the entire bill as repairs because the contractor's bank reference says “maintenance” would not explain the underlying work.
Keep the property business and the property detail clear
UK rental properties are generally brought together in one UK property business for Income Tax. Foreign property belongs in a separate business. A property reference remains useful for management and evidence, even though a separate quarterly submission is not normally required for every UK address.
HMRC's rental-income guidance explains the basic income and expense rules. For joint ownership, establish the share taxable on you before allocating receipts and expenses. The person whose account receives the money is not necessarily the person taxable on all of it.
Keep revenue costs, capital projects and residential finance costs identifiable. A mortgage payment can include a capital repayment and interest. Neither should be treated as an ordinary repair merely because it appears among the property's monthly outgoings.
For shared bills, use a reasonable allocation and retain the calculation. Do not claim the full same expense against several properties or owners. A property-level schedule should add back to the business totals and to the supporting statements. Those connections make it easier to answer a question about one address without losing sight of the portfolio as a whole.
Keep the evidence connected to the figures
Your digital record should explain the amount, date and nature of the transaction. Keep the invoice, receipt, statement or other evidence that supports it. A photograph can make a paper document easier to retain, but a folder of photographs alone does not create complete transaction records.
For sole traders, HMRC normally requires business records to be kept for at least five years after the relevant 31 January filing deadline. Keep them longer where the rules for a late return, enquiry or other circumstances require it. Check the record-retention guidance.
Make the records usable by your future self. Include a short explanation where a bank description is vague, retain the calculation behind a business-use split and make corrections traceable. For a missing receipt, try the supplier account, email confirmation or a replacement invoice before relying on incomplete evidence.
At review time, compare your records with the bank or payment account and investigate differences. Equal totals are useful, but two errors can cancel each other out. A sample of individual transactions can reveal a duplicated purchase or an omitted customer receipt that a totals-only check misses.
A review that checks more than the total
Start with coverage: the correct person, business and period, plus all relevant accounts and cash records. Then look at completeness. A feed can be connected today while still missing an earlier week. Confirm the earliest and latest transactions against the source.
Next, inspect unusual items. Large transfers, loan receipts, refunds, net settlements and private purchases often need more context than a bank description provides. Check for duplicate imports where a statement overlaps a live feed. An automatic warning is useful evidence to investigate, not proof that the entry must be removed.
Finally, review category totals. A category unexpectedly showing zero, a large increase or a negative amount deserves an explanation. You do not have to make every annual tax adjustment at this stage, but you should understand the records behind the summary you approve.
HMRC explains what quarterly updates contain. Keep the approved version and the resulting acknowledgement together. If something later changes, correct the source record and use the software's supported update process so you can explain which figures are current.
Resolve large projects before filing
Keep a project record with the before-and-after position, itemised costs and the treatment adopted. Identify insurance or deposit recoveries. Carry genuine technical questions into the annual review with the evidence needed to answer them.
Take the next step
Avona.app offers a self-service route from £15/month. Bring your records together, review the figures and choose a workflow that fits your business. For professional help, discuss the scope and total price of Avona Concierge, managed by chartered accountants, before choosing a service.